I recently spoke with Enjoy Digital and Yorkshire Building Society at Leeds Digital Festival 2026 to discuss customer trust, AI adoption and how financial services businesses should approach emerging technology.
The session was designed to explore the growing gap between the pace of technological innovation in financial services and the willingness of customers to embrace it.
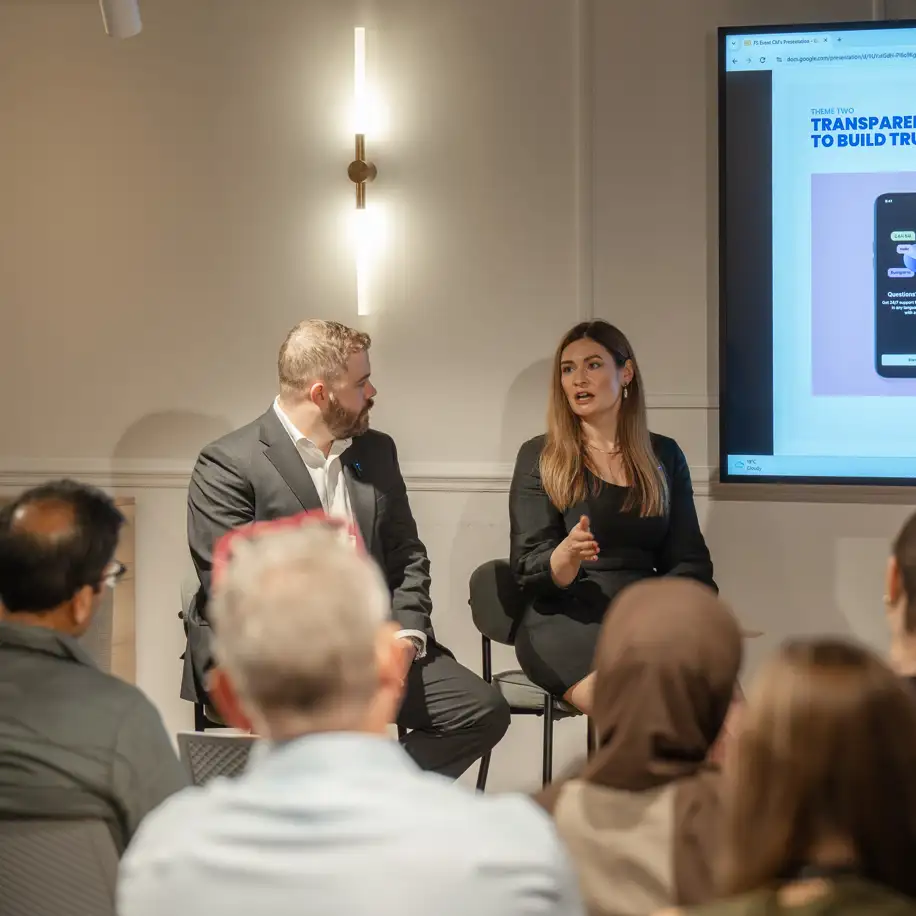
I was joined by Lauren from Yorkshire Building Society, with the discussion covering everything from customer perceptions of AI and regulatory oversight to the future of human interaction in financial services.
There was plenty we agreed on, although I found myself returning to a particular concern throughout the conversation. With so much pressure on businesses to adopt AI, are we spending enough time considering whether we’re applying it to the right problems?
What Enjoy Digital’s research tells us about customer trust
Enjoy Digital surveyed over 1,000 UK banking customers to understand their attitudes towards AI and technology in financial services.
A few findings stood out:
- 40% believe banks are moving too quickly with AI and technology adoption.
- 66% feel they lack transparency about how AI and their personal data are being used.
- 83% want FCA oversight of AI in financial services, rising to 90% among over 55s.
- 60% want to speak to a real person to verify decisions, while 40% would pay a premium for guaranteed human access.
What I found interesting was the difference between customers’ willingness to use technology for everyday financial tasks and their comfort with handing over more consequential decisions.
People are generally happy to use an app to check their balance, move money or pay bills. Letting an AI system autonomously make decisions that could affect their financial circumstances is another matter.
That seems perfectly reasonable to me.
We should be more selective about what we automate
One of the first questions put to the panel was how financial services brands can innovate at speed without compromising customer trust.
My view is that businesses should start by identifying opportunities where the consequences of something going wrong are relatively low.
There are plenty of administrative processes and routine interactions that could benefit from automation. Those are sensible places to start, particularly while the technology continues to develop and organisations build their understanding of its limitations.
I’m much less comfortable with the idea of rapidly deploying autonomous systems into processes where an incorrect decision could have serious financial consequences.
That caution also needs to extend to the way businesses think about their customers.
We discussed how different generations are becoming familiar with AI and how attitudes towards autonomous decision-making are likely to change. I expect those attitudes will shift considerably over time, especially as younger consumers who have grown up with AI become a larger part of the market.
But businesses need to be careful about making assumptions.
Customer personas that were developed a year or two ago might already be out of date. I made the point that we’re increasingly moving towards quarterly reviews of customer understanding because the technology, and people’s exposure to it, is changing so quickly.
AI transparency could become the next cookie banner problem
Another part of the discussion focused on how financial services businesses should communicate their use of AI.
Customers clearly want transparency, and quite rightly. I raised a concern, though, about how the industry might go about delivering it.
We’ve seen something similar with cookie banners and privacy notifications.
What began as an important exercise in helping consumers understand and control how their data is used has, in many cases, produced a fairly miserable digital experience.
Users are bombarded with consent notices, pop-ups and disclaimers. Eventually, the natural reaction is to dismiss them as quickly as possible.
I can see a risk of AI disclosures heading in the same direction.
There’s still no universally established approach to what should be disclosed, when a customer should be informed and how much detail is appropriate. As AI becomes more widely integrated into customer journeys, I suspect we’ll see greater standardisation.
I’d like to see businesses give some thought to the experience before we get there.
A useful disclosure should explain why AI is being used, what the customer gains from it and what alternatives are available. There’s little point in adding another notification that people instinctively close without reading.
Consumer Duty is a sensible place to start
Regulation was another prominent topic, particularly given the number of consumers who want greater FCA oversight of AI.
I suggested that we already have a useful principle to guide our approach.
The first cross-cutting rule of the FCA’s Consumer Duty requires firms to act in good faith.
I appreciate that’s a simplification of a much broader regulatory framework, but I think it’s a helpful starting point when considering new technology.
During the discussion, I used the example of a local GP practice that had introduced a chatbot to help manage appointment bookings. The change had prompted considerable criticism from patients on social media.
I suspect much of that frustration came from the circumstances in which the technology was being introduced.
People were already frustrated by appointment availability and waiting times. Introducing another automated interaction, particularly where patients felt they had little choice, was unlikely to improve their experience.
Healthcare and financial services have some similarities here. Both involve situations where people can feel vulnerable, and speaking to another person is often an important part of establishing confidence.
If you’re already struggling to get a GP appointment, being told by a chatbot that the next available slot is six weeks away could understandably make the experience worse.
It’s a useful example of why businesses need to think carefully about how technology changes the experience for the person using it.
Should customers have to pay extra to speak to a human?
One of the more surprising findings from the research was that 40% of respondents would pay a premium for guaranteed access to human support.
I felt quite strongly about this.
In wealth management, and particularly in financial advice, the personal relationship between an adviser and their client is central to the service.
At Titan Wealth, our ambition is to be the UK’s leading advice-led wealth management business. The advisers who build those relationships, understand their clients’ circumstances and help them make important financial decisions are fundamental to that proposition.
I can’t envisage a situation where we’d consider making access to a human adviser a premium feature.
We also discussed the implications for vulnerable customers. I think firms need to be particularly careful when deciding whether an AI-enabled interaction is appropriate for someone who has been identified as vulnerable.
That should involve a proper assessment, informed by evidence about the customers concerned.
There’s clearly a role for AI in improving the efficiency of financial advice, and we’re already seeing promising developments. But I believe the greatest opportunities will come from giving advisers more time to spend with clients.
Not everything needs to be solved with generative AI
Towards the end of the panel, we moved on to the operational opportunities presented by AI.
This is something I’ve been spending quite a lot of time thinking about.
We’re exploring a range of internal AI initiatives at Titan, including agentic workflows and opportunities to reduce the administrative burden on financial advisers.
Some of the work already being undertaken is saving advisers hours each week. That time can be redirected towards client relationships, more regular conversations and a better understanding of their changing circumstances.
I’m optimistic about what can be achieved here, but there’s a technical distinction I think more businesses need to understand.
Generative AI produces probabilistic outputs. Given the same input, it may produce different results, and those results aren’t guaranteed to be correct.
Deterministic systems behave differently. You define the rules, and the same inputs produce the same outputs.
For processes where consistency and predictability are essential, deterministic automation can be a much more appropriate solution.
I’ve noticed a tendency for some businesses to approach almost every automation opportunity through the lens of generative AI. Given the attention the technology is receiving, I can understand why.
But there are plenty of problems where established technologies can deliver a more reliable result, often with less complexity.
Selecting the right approach requires a reasonable understanding of the difference, especially when we’re operating in regulated environments.
It’s an area I’ve been advocating for internally, and one I expect to spend more time on as AI becomes a bigger part of everyday business operations.
Demonstrating the value of AI
As we wrapped up the discussion, we were asked what else financial services businesses should consider when introducing AI.
My final point was about demonstrating value.
I suspect there are more AI solutions being introduced without a clearly articulated customer benefit than we’d expect.
I’ve seen how quickly enthusiasm for a particular technology can start to influence the solutions businesses develop. Sometimes that enthusiasm gets ahead of the problem we’re supposed to be solving.
I’d like to see organisations spend more time assessing the actual benefit being created and communicating it clearly to the people affected.
If we’re asking customers to accept a different experience because we’ve introduced AI, we ought to be able to explain why that experience is better.
And if we can’t, perhaps we need to reconsider whether it’s the right solution.
Watch the panel discussion
Thanks to Enjoy Digital for inviting me to take part in the discussion as part of Leeds Digital Festival 2026, and to my fellow panellists for sharing their perspectives.
The full session includes more detail from Enjoy Digital’s consumer research, along with our discussion of customer expectations, AI governance, regulation and the future of human interaction in financial services.
Watch the full Technology Trust Gap in Financial Services panel discussion >>